
Lenders financing the AI build-out are committing billions against hardware they cannot independently verify. The collateral—advanced semiconductors—is real, but its performance is not. This creates a blind spot in credit risk that power markets solved decades ago.
The Collateral Visibility Gap
When a borrower pledges GPUs as security, lenders typically confirm that the hardware exists, who owns it, and whether other parties have claims on it. These controls are not sloppy. Collateral is audited, liens are perfected, and covenants are drafted by experts.
But none of that answers a more fundamental question: what did each specific GPU actually do last month, and how much revenue did that work generate? Under current arrangements, there is no standard way for a borrower to prove utilization or output to a lender—even if the borrower consistently ran its GPUs at an 80% to 90% rate.
This is not a data problem. Data centers continuously log power draw, utilization, thermals, and uptime. The problem is that this data cannot be handed to lenders in a format they can easily verify, tied to specific GPUs and specific customer contracts. Lenders are left taking the borrower’s word for it.
The Scale of the Market
Private credit lending to AI has reached well beyond $200 billion, according to a February Bloomberg report. The Bank for International Settlements expects this amount to hit between $300 and $600 billion by 2030. CoreWeave alone carries more than $21 billion of this debt.
The trend began three years ago when CoreWeave borrowed $2.3 billion against Nvidia H100 GPUs, led by Magnetar Capital and Blackstone. That was the first time H100s were pledged as security. A little more than a year later, over $11 billion had been raised this way.
Depreciation and Utilization Risks
GPU collateral does not hold value like traditional assets. Nvidia shipped Ampere, Hopper, and Blackwell in only four years, and CEO Jensen Huang has said the company is on a “one-year rhythm” now. A five-year loan financed against a GPU today will see at least three new generations before it matures.
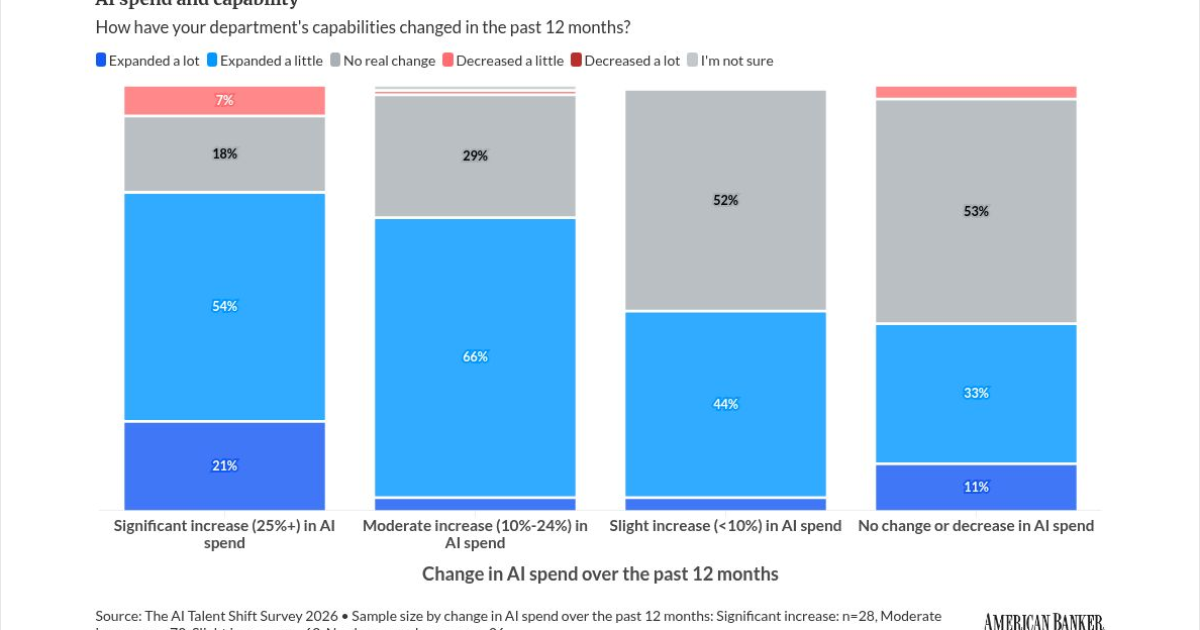
Utilization adds another layer of uncertainty. Despite the AI boom and the high costs of large language models, Cast AI’s recent enterprise survey found that average GPU utilization stood at only 5% across thousands of surveyed companies. Even borrowers with strong utilization have no standardized way to prove it.
How Power Markets Solved This
Market players in power finance worked this out decades ago. Instead of borrowing on turbine blades, lenders advance against megawatt hours—all metered independently and settled through the grid. The collateral is not the equipment; it is the verified output.
This formula translates directly to the GPU market. The GPU delivers computing power to customers under contract, and that output is the exact thing that repays the loan. The measurement infrastructure already exists in every data center.
A Path to Standardized Reporting
Credit agreements can be structured so that standardized performance reporting reaches the lender, with delivered GPU output matched against counterparty contracts. Rather than leaving every lender to work this out deal by deal, regulators can fast-track common reporting standards, similar to those used in aviation or the power industry.
Lenders that require verified data in underwriting and ongoing monitoring—on GPU utilization, uptime, and actual compute delivered under customer contracts—will see exactly how the collateral is performing and what cash it is throwing off. They will be best positioned to lead this fast-growing market.