

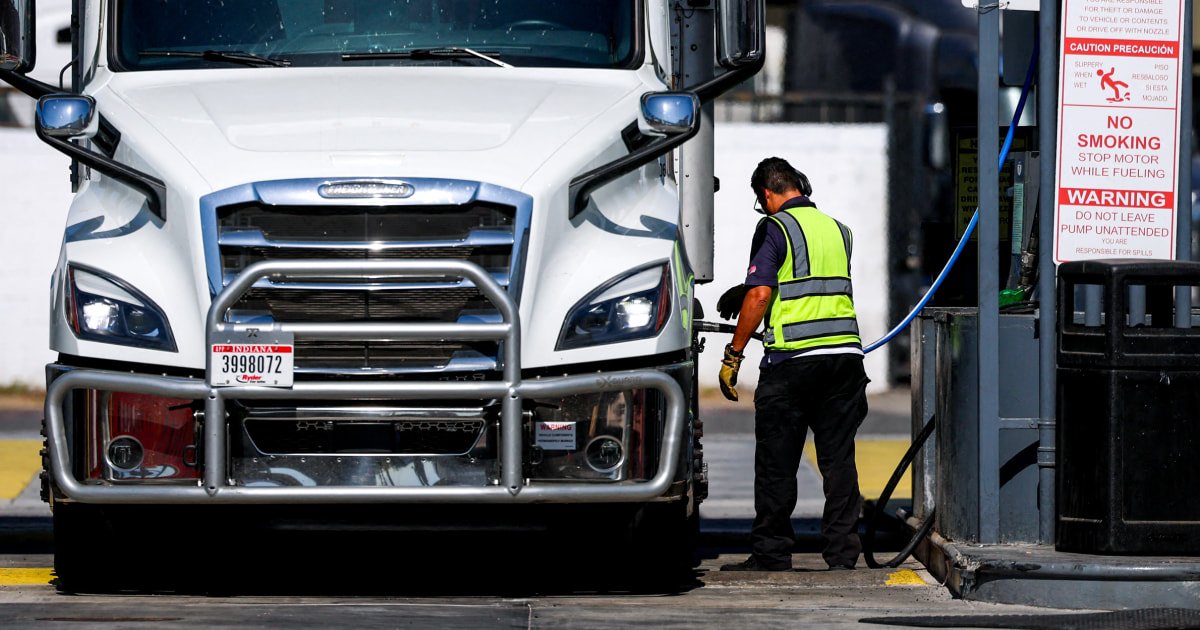
Crude oil prices extended their rally for a fourth consecutive trading session on Thursday, contributing to a monthlong surge that has driven diesel fuel costs to their highest level since 2022. The national average price for diesel hit $5.78 per gallon on Thursday morning, marking a 53% increase since late February when the conflict with Iran began. At that time, diesel was averaging $3.76 per gallon nationwide.
Gasoline prices also rose, with the national average for unleaded fuel reaching $4.14 per gallon, up two cents from the previous day, according to AAA data. These retail price increases follow the continued upward movement in crude oil prices, with the international benchmark Brent surpassing $97 per barrel on Thursday morning, nearly 10% higher than the start of the week.
Why Diesel Prices Matter
Experts are particularly focused on diesel this week because it powers essential sectors such as agriculture, transportation, and shipping. From farm equipment to 18-wheelers, diesel is critical for planting and harvesting crops globally. As a result, higher diesel prices now could translate into increased grocery costs later in the fall.
Key Drivers Behind the Energy Price Surge
Several factors are contributing to the global rise in energy prices, with the ongoing conflict in Iran being the most significant. The war has disrupted major maritime routes for oil and gas, particularly the Strait of Hormuz, where recent attacks on ships and retaliatory U.S. strikes have drastically reduced daily vessel traffic. Before the conflict, the strait facilitated the passage of about 20% of the world’s oil supply.
Additionally, the escalation of the Ukraine war has added pressure. Ukrainian drone attacks on Russian refineries prompted Russia to ban diesel exports until the end of September, citing domestic supply concerns. As the world’s second-largest diesel exporter, Russia’s actions have disrupted global supply, with combined disruptions accounting for roughly 20% of seaborne diesel trade.
Potential Relief and Market Reactions
Analysts suggest that meaningful relief could come from either increased oil and gas flow through the Persian Gulf or a resumption of Russian exports. However, recent comments from President Donald Trump, who indicated that U.S. strikes on Iran would not last long but that further action was possible, did little to ease price pressures.
Estimates of Persian Gulf oil export recovery vary, with Goldman Sachs Research suggesting about two-thirds of pre-war levels, while ING estimated around 50%. These figures have not provided much comfort to energy markets, as wholesale gas and natural gas prices both rose by 1% in early Thursday trading.
Broader Economic Implications
The energy price shock has fueled expectations among investors that inflation will remain elevated, driving up U.S. Treasury yields. Although bond yields dipped slightly on Thursday, the average 30-year fixed mortgage rate reached 6.91% late Wednesday, indicating persistent financial pressures.
Federal Reserve Governor Christopher Waller expressed a cautiously optimistic view, stating that he expects upcoming inflation readings to be “reasonable,” suggesting that energy prices have not yet bled into other goods and services. However, he noted that if August inflation data comes in hot, a rate hike could be considered. Quoting John Lennon, Waller said, “Give disinflation a chance.”