
Reputation management has never been optional for banks, but the rise of artificial intelligence as a powerful new stakeholder has raised the stakes. AI platforms can instantly reach millions of people and shape their judgments—and ultimately their behavior—making them a central player in the stakeholder ecosystem.
People increasingly turn to AI to research companies, including banks. According to research from the American Banker 2026 Most Reputable U.S. Retail Bank study, about one third of the general public is very likely to use AI tools for banking-related purposes, such as comparing banks and understanding fee structures. That share rises to over four in 10 among younger audiences, even though AI ranks among the least-trusted sources for this kind of information.
AI searches about banks analyze information from a wide variety of sources, both bank-owned and not. The AI platforms themselves decide which sources to prioritize, interpret the content, and render a verdict on how reputable a bank is and how it performs across different parts of the business. Yet most companies struggle to answer critical questions: How is AI portraying the company? What narratives does it amplify or suppress? What sources does AI base its assessments on—and are they accurate? How prominent is the company’s voice in shaping the narrative that AI returns?
AI Rates Banks Lower Than the Public Does
Using data from the 2026 study, researchers compared AI-based judgments from Claude, ChatGPT, and Gemini with perception-based assessments from the informed general public. The same set of questions from the RepTrak normative framework was used, evaluating reputation and perceived business performance across 23 factors grouped into seven drivers: products & services, innovation, workplace, conduct, citizenship, leadership, and performance.
For illustrative purposes, a mix of institutions was selected: Ally Bank, Bank of America, Chase, Chime, TD Bank, Truist, and Wells Fargo.
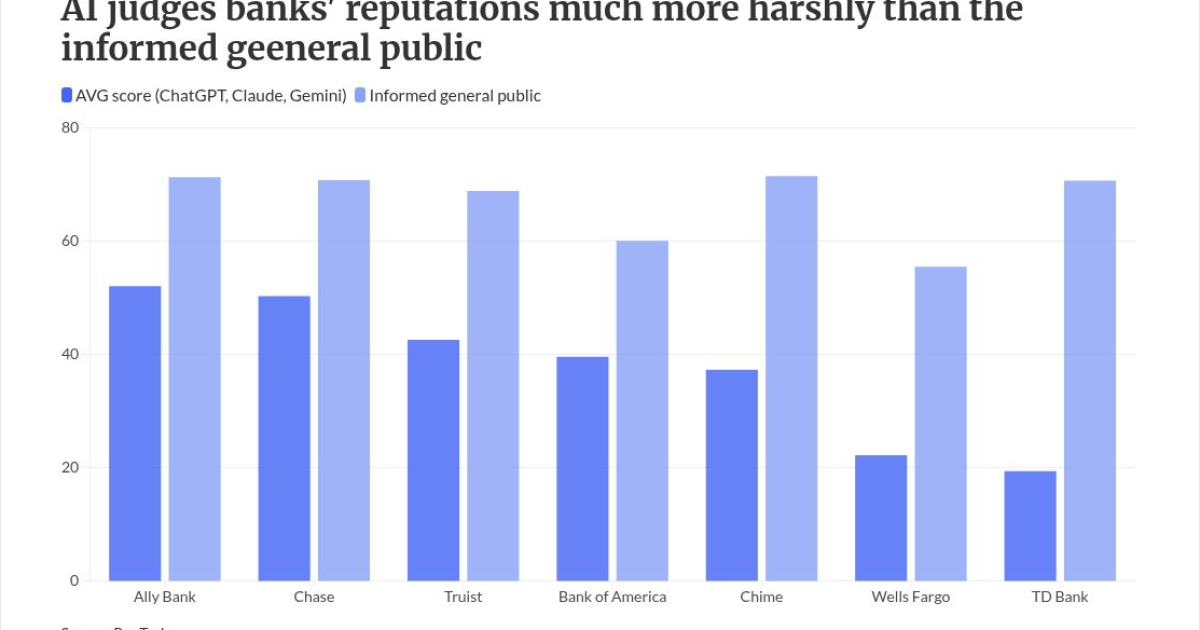
The first key finding: AI judges banks’ reputations much more harshly than the informed general public.
Among the measured banks, Ally Bank was rated most positively by AI on a 100-point scale (averaged across all three platforms) but at a relatively low level of 52.1. It was followed by Chase at 50.3, Truist at 42.6, Bank of America at 39.6, Chime at 37.3, Wells Fargo at 22.2, and TD Bank at 19.4.
The informed general public consistently scored the same banks higher, with an average of 70.0, ranging from 55.5 for Wells Fargo to 71.5 for Chime. Neither bank type nor human rating levels were consistently correlated with AI reputation assessment.
AI Is Harshest on What Matters Most
A second insight: AI-based driver scores were also lower relative to survey-based perceptions in areas that matter most to consumers—products/services, conduct, and citizenship. Only banks’ financial performance was shown in a more positive light.
The reputation drivers AI judges banks on most harshly are those the public cares most about when evaluating banks’ reputations. The average AI-evaluated conduct score was 26.1 versus 68.0 for the informed general public; products/services scored 42.0 versus 71.0; and banks’ citizenship credentials were rated 50.4 versus 66.3.
AI is especially critical of banks not standing behind their products and services, their lack of ethical behavior, and environmental shortcomings.
Perceived financial performance was the only driver that received a significantly higher AI-based score, earning an average rating of 81.5 compared to an average human rating of 72.3. Banks’ profitability stood out as the most positively evaluated factor.
No Single Bank Wins on All Drivers
A third insight: no single bank “wins” on all reputation drivers, and legacy actions matter much more to AI platforms than to humans.
While Ally received the highest scores for four out of the seven drivers of reputation, other banks rose to the top for the remaining ones. For example, Bank of America was rated highest on innovation and financial performance, while Chase came out on top in the leadership category.
Bank-Owned Sources Are a Small Share of AI Inputs
A final insight: when AIs create their assessments of banks, bank-owned sources make up less than 10% of the information they consult.
The most frequently cited source was the news media, followed by websites that produce rankings, like J.D. Power and Glassdoor. Other sources consulted included government websites, such as the Consumer Financial Protection Bureau, and public customer reviews and social media accounts.
Banks need to understand which sources are most impactful for their reputation—including by AI platform type—and how much their own voice is breaking through. This is especially critical as respondents from RepTrak’s 2026 Most Reputable US Retail Bank study indicated that they see banks’ websites and apps as the second most trusted source of information after word of mouth.
What Banks Can Do
Reputation management was never optional—especially for banks—and the emergence of AI as a new, central stakeholder with significant reach and influence has raised the stakes even further. The findings provide strong preliminary evidence that banks, whose reputations have historically faced pressure in the court of public opinion, are facing an additional challenge through the lens of AI. Notably, AI judges banks most harshly in the areas that matter most to consumers: products/services and conduct.
With banks’ own voices still accounting for a relatively small share of the sources AI platforms draw on—including both recent and legacy content—they must redouble efforts to ensure their perspectives are authentic, accessible, and readily discoverable. Doing so will help reinforce AI-identified strengths, address areas of weakness, and build a credible, evidence-based narrative around the issues that matter most to stakeholders.